Are all loans eligible for mortgage insurance removal?
No, not all loans are eligible. Government-backed loans including FHA, USDA (RHS) and VA loans do not allow mortgage insurance cancellation. It is required for the life of the loan.
If you have a conventional loan, you may be eligible to remove the Private Mortgage Insurance (PMI) requirement if you have been paying your monthly mortgage payments on schedule and your mortgage has reached the required loan balance. Please continue reading to learn about other eligibility requirements that may apply to your conventional loan.
For fixed-rate loans: the required loan balance is based on the initial amortization schedule.
For adjustable-rate loans: the required loan balance is based on the amortization schedule then in effect.
Two paths to PMI removal for conventional loans:
Automatic termination: If you are not behind on any payments, your PMI will automatically terminate when the principal balance of the loan is scheduled to reach 78% of the original property value.
If your loan is not current when the principal balance of the loan is scheduled to reach 78% of the original property value, PMI will automatically terminate on the first of the month following the date on which your loan becomes current.
Request early PMI cancellation: You may be able to cancel your PMI before your loan satisfies the requirements for automatic termination.
To qualify, any loan must meet the following basic criteria:
No payments are currently past due.
You have a good payment history, meaning no payments have been 30+ days past due in the past 12 months or 60+ days past due in the past 24 months.
The principal balance of your loan must have reached the required percentage of either the original value OR current value of the property—known as the Loan-to-Value percentage:
Original Value:
You may request cancellation based on the original value of the property based on one of the following:
You may be eligible when your principal balance reaches 80% of the original property value – meaning either the contract sales price or appraised value of your home at closing, whichever is lower (or, if you have refinanced, the appraised value at the time you refinanced).
Your original amortization schedule shows the date on which the principal balance is first scheduled to reach 80% of the original property value—log into your account and go to My Loan to see the amortization schedule. Alternatively, you may choose to make one or more additional payments to your principle to achieve the 80% LTV requirement ahead of schedule.
Current Value:
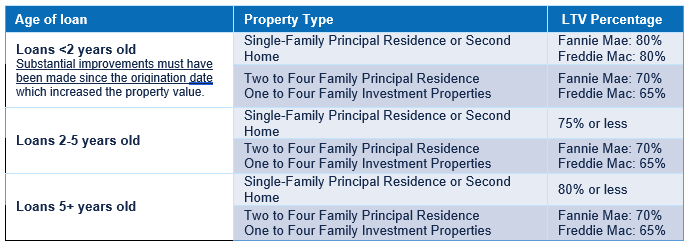
Depending on the owner of your mortgage loan and any applicable state laws, your loan may satisfy the LTV requirement at any time based on the current value of your property – see table below.
In all cases, the LTV must be verified by a property valuation based on an inspection of both the interior and exterior of the property. Customer Care will provide you with the estimated cost of the appraisal, collect the amount from you, and order the appraisal on a mutually agreeable date.
Eligibility based on current property value: