


365 days later: Homeowners are saving hundreds on their monthly mortgage
Will it get any better than this? Compared to last year's rate, today's rate drop may make your monthly mortgage payment up to $486 cheaper.
First-Time Homebuyer, Buying a Home, Home Ownership, Mortgage Rates, Refinance, Selling a Home


Mortgage rates have dropped over a full percentage point within the past year, hitting new lows 16 times. This is a strong driver toward homeownership: Today's lower rates give consumers even more benefits.
Let's take a look at the top three:
Downsize or move up. Low rates open up opportunities to sell and move into a new house, whether it's bigger and better or smaller and located in a more desirable place. You could put your equity gains (soaring to an impressive average of $17,000) from your current home toward a new down payment — securing more room if you're working at home or have kids learning remotely.
Purchase your first home. The non-financial and financial benefits of becoming a homeowner are well-documented. But what matters is deciding when the timing is right. This is only for you to determine, but it may help to know that now is an ideal time to purchase if you feel that other factors fall into place. Take a closer look at how much it could cost you to wait.
Refinance. If you're already a homeowner, it may be helpful to think about refinancing. This can be a smart way to lock in a lower rate, along with a lower monthly payment, and see substantial savings over time. But upfront closing costs may also apply. You can read on to answer the question: Is refinancing right for you?
Why 2021 could be a great year for anyone who's ready to buy
A little over a year ago, mortgage rates were significantly higher, sitting at around 3.93 percent. You, like many people, may have been waiting for market conditions to improve to make your move. Current record-low rates have helped homeownership to become more affordable and attainable than it was just one year before.
This chart depicts how much you might save when buying at today's (early 2021) rates compared to the amount you could have paid last year, also depending on your home's purchase price:
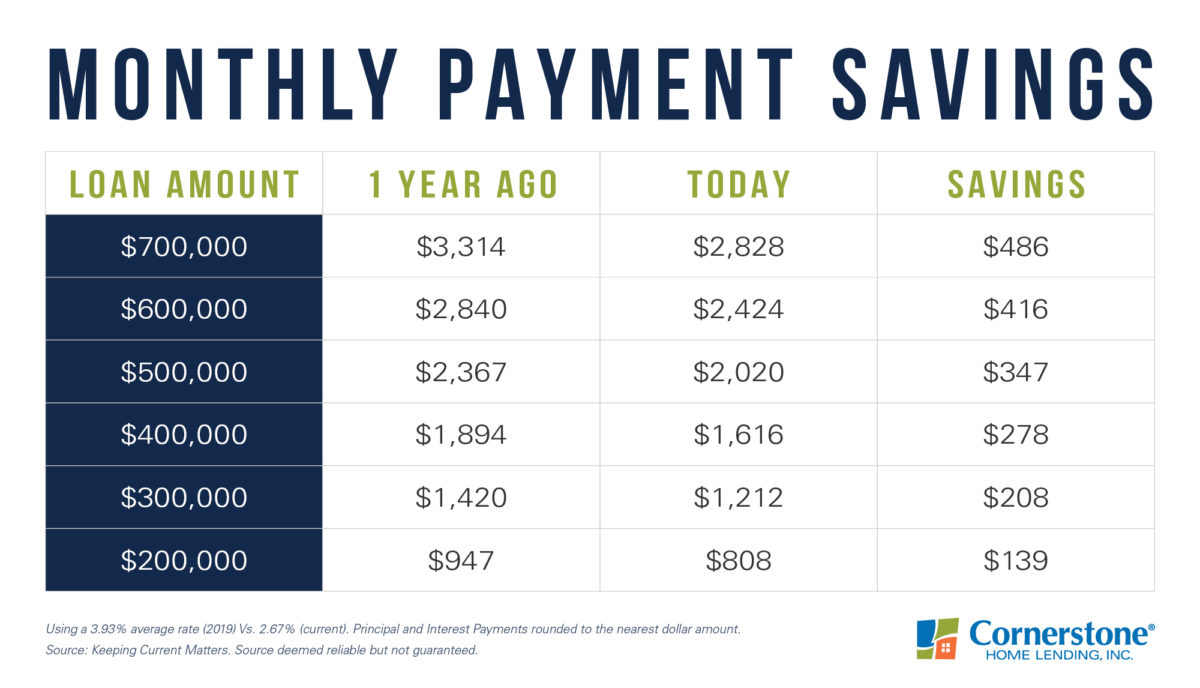
This is a time when you're likely to get more house for your money and may also pay less each month for your mortgage.
First-Time Homebuyer, Buying a Home, Home Ownership, Mortgage Rates, Refinance, Selling a Home


 405-896-5219


