


Believe these 2 myths to make homebuying harder than it has to be
If you're a first-time homebuyer with low credit score rating, go ahead & get excited. Busting 2 myths takes pressure off buying & puts owning within reach.
Credit Score, Current Events, First-Time Homebuyer, Getting Prequalified, Buying a Home


Freddie Mac's 2019 report, Perceptions of Down Payment Consumer Research, has big implications for first-time homebuyers. Read these truths if you feel like there are hurdles to homeownership standing in your way.
"For many prospective homebuyers, saving for a down payment is the largest barrier to achieving the goal of homeownership. Part of the challenge for those planning to purchase a home is their perception of how much they will need to save for the down payment…
Based on our recent survey of individuals planning to purchase a home in the next three years, nearly a third think they need to put more than 20 percent down."
Homebuying really can be easy when 2 major myths are busted
Because of two common misconceptions, most of today's renters have a hard time seeing homeownership as within their reach:
Myth #1: You must have 20% down to buy
It's common for homebuyers to overestimate how much they actually need to qualify for a mortgage. According to Freddie Mac's research, 22 percent of renters and 31 percent of homeowners think a mortgage lender will require them to pay a down payment of 20 percent or higher of a home's purchase price.
Also:
"If a 20 percent down payment was required, 70 percent of those who were planning to buy a home in the next three years said it would delay them from purchasing. Nearly 30 percent indicated they would never be able to afford a home."
Plenty of people may believe that 20 percent down is required to buy their dream home. But these potential buyers might not know about the many mortgage programs available with down payment requirements as low as a 3-percent minimum. So, renters on hold could actually start house-hunting much sooner than expected.
Myth #2: You must have a FICO score of 780+ to buy
Whether it's a lack of information or misinformation, too many first-time homebuyers believe that there's a "good" credit score requirement of 780 or higher needed to purchase.
The recent Origination Insight Report from Ellie Mae debunks this myth, offering up data from recently approved — and closed — mortgages:
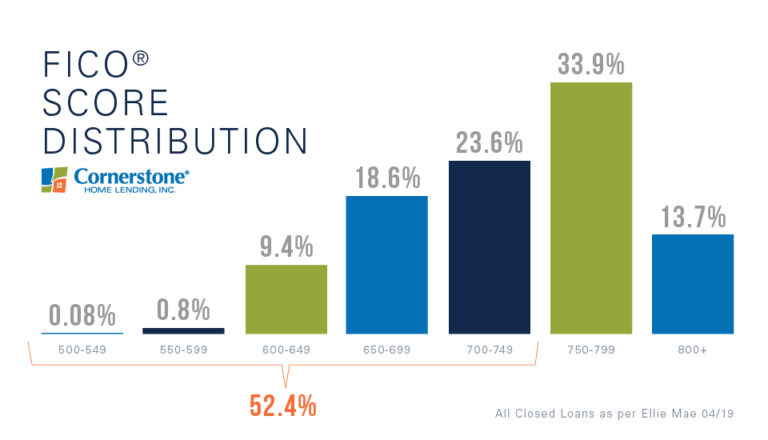
As the chart above shows, over half, or 52.4 percent, of approved home loans had reasonable credit score ranges from 600 to 749.
That feeling when you're home in 10
A smaller down payment + a low credit score requirement = A happy homebuyer who gets home in 10 days. Add to that the fact that mortgage rates have recently hit record lows, and you might be feeling invincible.
Credit Score, Current Events, First-Time Homebuyer, Getting Prequalified, Buying a Home




