


At least 8 great reasons to fall in love with homeownership
Are there benefits to being a first time home buyer? Just in time for Valentine's, here are 8 reasons to fall for homeownership this year. 💖


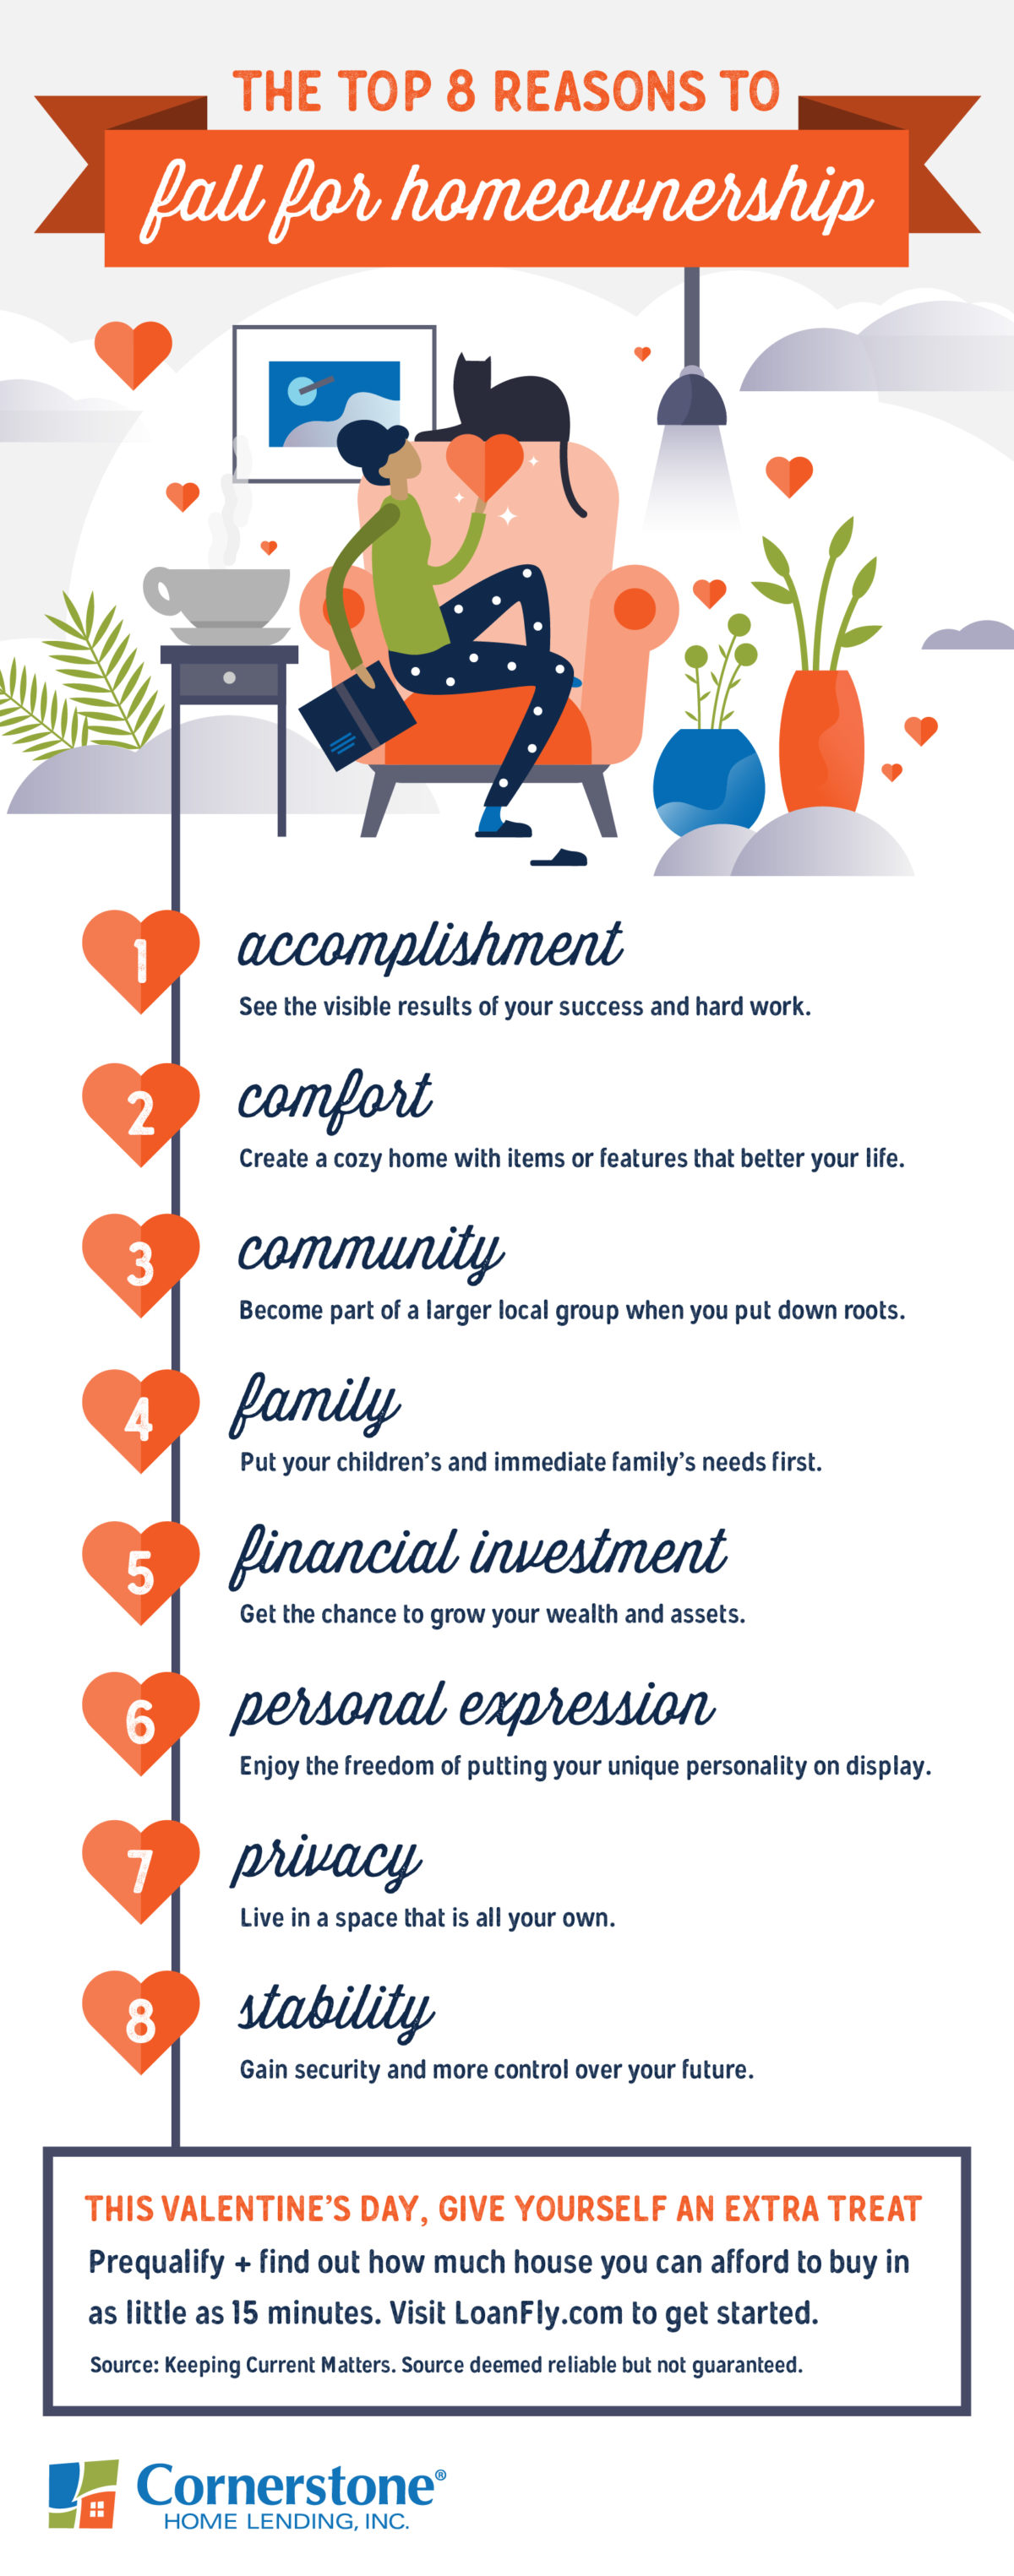
These are the top takeaways:
Homeownership can literally pay off, increasing your net worth up to 40-times that of a renter.
Factor in the many other benefits, and you'll see that the advantages of owning a house extend far past the financial.
Which reasons do you identify with that make you want to own your own house?
Why it makes more sense to buy now and not later
Whether you're a renter who's ready to reap the benefits of homeownership or a homeowner who's outgrown your current living space, it may help to know that market conditions don't support putting off your purchase.
Two straightforward questions can bring clarity and may make it easier to decide if you should buy a home now or later:
How much will home prices increase this year?
How much will mortgage rates increase this year?
To answer the first question, let's take a look at what three major housing authorities have forecasted for 2022's home price appreciation:
Mortgage Bankers Association: 5.1 percent
Freddie Mac: 7 percent
Fannie Mae: 7.4 percent
The National Association of REALTORS® (NAR) finds today's median home price to be $358,000. Averaging these three predictions at 6.5 percent indicates that the current price of a $358,000 house may rise in value to $381,270 by the end of the year.
Waiting to buy a home, then, could cost you as much as $23,270.
What about mortgage rates? The current 30-year fixed mortgage rate has risen above 3 percent. Most authorities project that mortgage rates will increase as the economy continues to recover.
The same housing authorities have also provided their 2022 rate forecasts:
Fannie Mae: 3.4 percent
Freddie Mac: 3.7 percent
Mortgage Bankers Association: 4 percent
The average of all three forecasts is 3.7 percent. Even a slight uptick in mortgage rates has the potential to increase your monthly housing cost.
And should both home prices and mortgage rates rise as expected, you can anticipate paying significantly more for your monthly mortgage. If you buy a $358,000 house at today's rate of 3.55 percent/3.73 Annual Percentage Rate, with a 10-percent down payment, you'd pay $1,618 for your monthly mortgage.*
(Note that this does not take into account taxes, insurance, and other fees that vary based on location.)
Fast-forward to the end of the year, and the same home may cost $381,270 with a mortgage rate of 3.7 percent/3.88 Annual Percentage Rate, as forecasted above. After putting down 10 percent, you may pay $1,755 for your monthly mortgage.*
This adds up to an extra $137 a month, $1,644 a year, or $49,320 over the life of your mortgage.
Don't forget about the $23,270 in equity gains you'd miss out on by purchasing the same home later in the year. By buying now, you may see a total wealth increase of $72,590 ($23,270 in projected equity gains plus $49,320in potential mortgage savings).
While the financial benefits are undeniable, the infographic above is a strong reminder of why so many homebuyers fall head over heels for homeownership. Its non-financial benefits are just as enticing.




